2027 Wealth Planning in Kerala: Why NRI Money Is Flowing Back Into Structured Local Advisory
 General
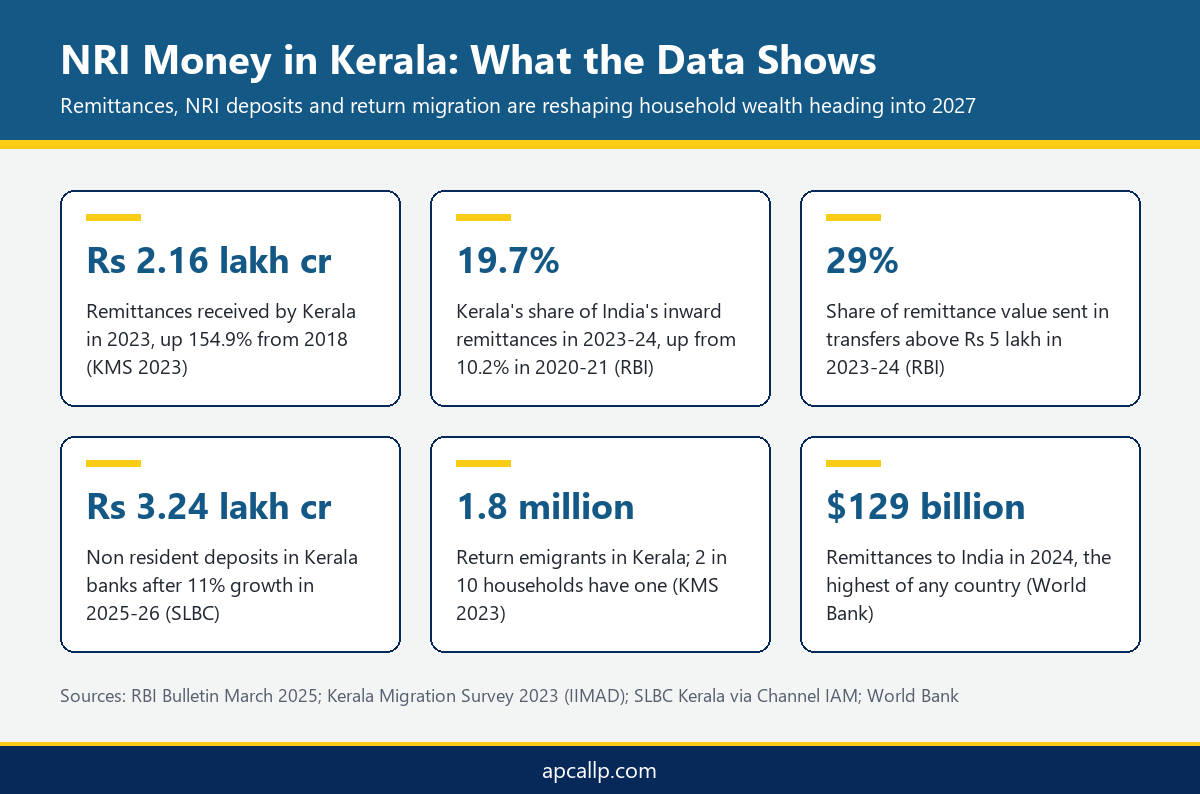
Kerala now receives nearly a fifth of all money Indians send home, with its share of national inward remittances rising to 19.7% in 2023-24 according to the Reserve Bank of India's sixth remittances survey. For many families, that money ends up spread across deposits, property and policies rather than in a single plan. As families prepare for 2027, many are asking for one joined up view of taxes, investments and the return home. If that sounds like your household, you can speak with the APCALLP team in Kochi, Kozhikode or Bengaluru before the year closes. This guide explains why structured local advice is gaining ground and how a year end portfolio review advisor Kochi families can rely on fits into that shift.
Key Takeaways
- Remittances, NRI deposits and return migration in Kerala have all grown sharply, which makes a year end portfolio review advisor Kochi based households can meet in person more useful than ever.
- A mutual fund portfolio review before 2027 should check residency status, tax treatment and overlap across funds held from abroad.
- Families planning a return should pair investment advice with a retirement planning consultant near me Kochi search that leads to qualified, regulated professionals.
What the Numbers Say About NRI Money in Kerala
Kerala's diaspora is sending home more money than ever, and a large share of it arrives in big transfers. That pattern points to savings meant for long term goals rather than monthly household support.
The Kerala Migration Survey 2023 key indicators estimate that Kerala received Rs 2.16 lakh crore in remittances in 2023, up 154.9% from 2018. The same survey counts 2.2 million emigrants and 1.8 million return emigrants, and finds that two in every ten Kerala households have a return emigrant. The RBI survey adds that remittances above Rs 5 lakh made up around 29% of total value in 2023-24. Bank data tells a similar story. Non resident deposits in Kerala banks rose 11% in 2025-26 to about Rs 3.24 lakh crore, according to a State Level Bankers' Committee review reported by Channel IAM. Globally, the World Bank estimated that India received $129 billion in remittances in 2024, the most of any country.
Read together, these figures describe a state where household wealth can grow faster than household planning. Larger transfers, rising deposits and a big returning population all create decisions about tax, liquidity and where money should finally rest. The RBI survey also notes that advanced economies now send a larger share of India's remittances than the Gulf, which suggests more skilled migrants with higher savings and longer horizons. For Kerala families, that mix is the clearest reason the 2027 outlook favours structured, local advice.
Why NRI Families Are Moving From Scattered Assets to Structured Local Advice
Large balances bring complex questions. Once savings cross a certain size, the cost of poor structure usually outweighs the cost of good advice.
Many Kerala families built wealth in layers. A fixed deposit opened during one visit home, a plot bought through a relative, an insurance policy sold by a friend and a few mutual funds started online from Dubai or London. Each made sense alone. Together they rarely add up to a plan. A remitting family now often holds assets in two countries, faces tax rules in both and has no single person who sees the whole picture. This is where structured local advice earns its place. An advisor based in Kerala can meet parents who manage the money at home, coordinate with the family abroad and track Indian rules as they change. Our investment advisory services cover portfolio planning, diversification and risk assessment, working alongside the firm's chartered accountants. For many households, the outlook for 2027 is less about chasing returns and more about bringing order to what they already own.
What a Year End Portfolio Review Should Cover for NRIs
A December review gives you time to act before the financial year ends in March. For NRI and returning families, it should go well beyond checking last year's returns.
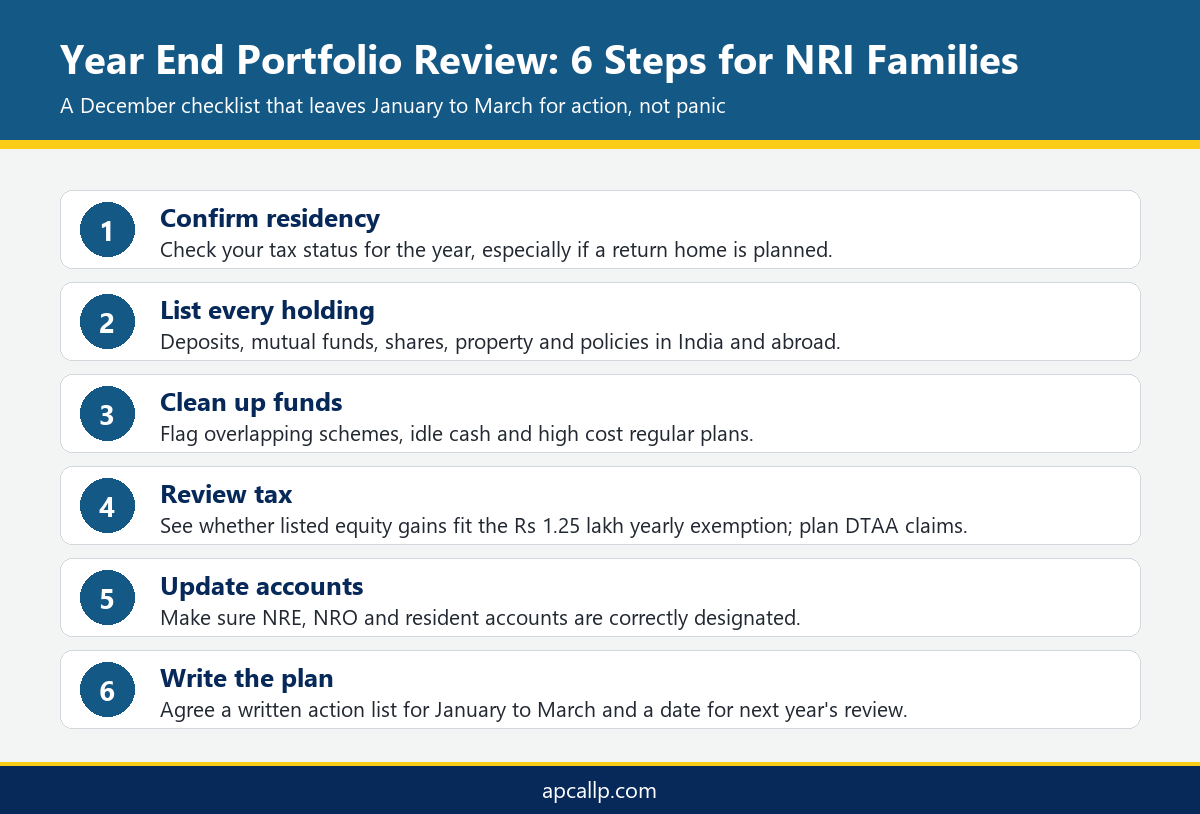
Start with residency. Your tax status for the year decides how income and gains are taxed, and a planned return can change it. Next, list every holding in India and abroad, including deposits, mutual funds, shares, property and policies. A mutual fund portfolio review before 2027 should flag overlapping schemes, idle cash, high cost regular plans and funds that no longer suit your goals. Check whether gains on listed equity can be booked within the yearly Rs 1.25 lakh long term exemption. Then confirm that NRE, NRO and other accounts are correctly designated, since returning residents must update their account status with banks. Our tax consulting team handles NRI returns, DTAA benefits and capital gains on property sales. A year end portfolio review advisor Kochi families meet face to face can bring all of this into a single written action list.
Timing matters as much as content. A review held in December leaves January and February to switch funds, book gains or losses and gather documents, with March kept free for checks rather than fresh decisions. It also lines up with the annual habit of rebalancing at the start of a new calendar year. Families who complete a mutual fund portfolio review before 2027 begins can start the year with a cleaner portfolio, fewer schemes to track and a clear view of the tax they are likely to owe. Keep notes from each review, because comparing them year on year shows whether the plan is actually working.
Planning the Return Home: Retirement, Property and Compliance
Return migration is now a planning event in its own right. The KMS 2023 indicators list retirement among the stated reasons emigrants come back, alongside job loss and low wages.
Coming home changes almost every part of a financial plan. Income may fall while health and family costs rise. Money parked abroad may need to move back, and assets bought as an NRI may now be taxed differently. Before searching for a retirement planning consultant near me Kochi, write down three numbers: what you will spend each month, what income you can count on and how long your savings must last. A good advisor turns those numbers into a withdrawal plan, a safety buffer and an asset mix you can live with. Property is often the largest asset for Kerala families, so decide early whether to keep, rent or sell it. Cross border movements of money and assets also carry regulatory steps, and our compliance services help align these with FEMA and RBI rules. The earlier these decisions are made, the less likely a return home becomes a rushed sale or a surprise tax bill.
How to Choose the Right Advisor in Kochi
Credentials, conflicts and communication matter more than promises. A short checklist helps you separate genuine advice from product selling.
First, check registration. Investment advice in India should come from SEBI registered advisers, and tax work from qualified chartered accountants. Ask how the advisor is paid, because fee based advice reduces the pull toward commission products. Look for someone who will explain what not to buy, put recommendations in writing and review the plan at least once a year. For NRI families, ask whether investment, tax and compliance teams work together, since a fund switch, a property sale or a return home can affect all three at once. You can read more about our firm and team, which serves clients from Kochi, Kozhikode and Bengaluru. If a retirement planning consultant near me Kochi search brings up many names, shortlist two or three and ask each for a sample review report before you commit.
Conclusion
Kerala's remittance boom has created real wealth, but wealth spread across countries, accounts and products needs structure to last. The data on remittances, NRI deposits and return migration all point the same way: more families are reaching the point where a professional, joined up plan pays for itself. Use this December for a careful review of residency, holdings, taxes and account status, and decide what your return home should look like. Working with a year end portfolio review advisor Kochi based families can visit makes that process far simpler. When you are ready, book a consultation with our advisors and enter 2027 with a clear plan.
Frequently Asked Questions
Why should NRIs work with a year end portfolio review advisor Kochi based?

What should a mutual fund portfolio review before 2027 include?
Why is NRI money in Kerala moving toward structured advice?
Can NRIs invest in Indian mutual funds?
What happens to NRE and NRO accounts when I return to India?
When is the best time for a year end portfolio review?
How do I find a good retirement planning consultant near me Kochi?
How are NRIs taxed on Indian investment income?
Should returning NRIs sell property in Kerala before moving back?
Does APCALLP help NRIs with tax and investment planning?